Troubleshoot · money
Tiranga withdrawal and payment problems
Direct answer
Check that the amount is within your withdrawable balance and your KYC is done. Then message in-app support once with the order ID. Don’t deposit more while you wait, and never pay a fee to “release” money. If it shows “successful” but nothing reached your bank, or you were asked to pay, report to 1930.
Withdrawal problems are the most common Tiranga complaint by far. Some have ordinary explanations, like un-wagered bonus money or a typo in bank details. Others don’t. This page helps you tell the difference, collect the right evidence, and escalate in the right order.
First: available vs withdrawable balance
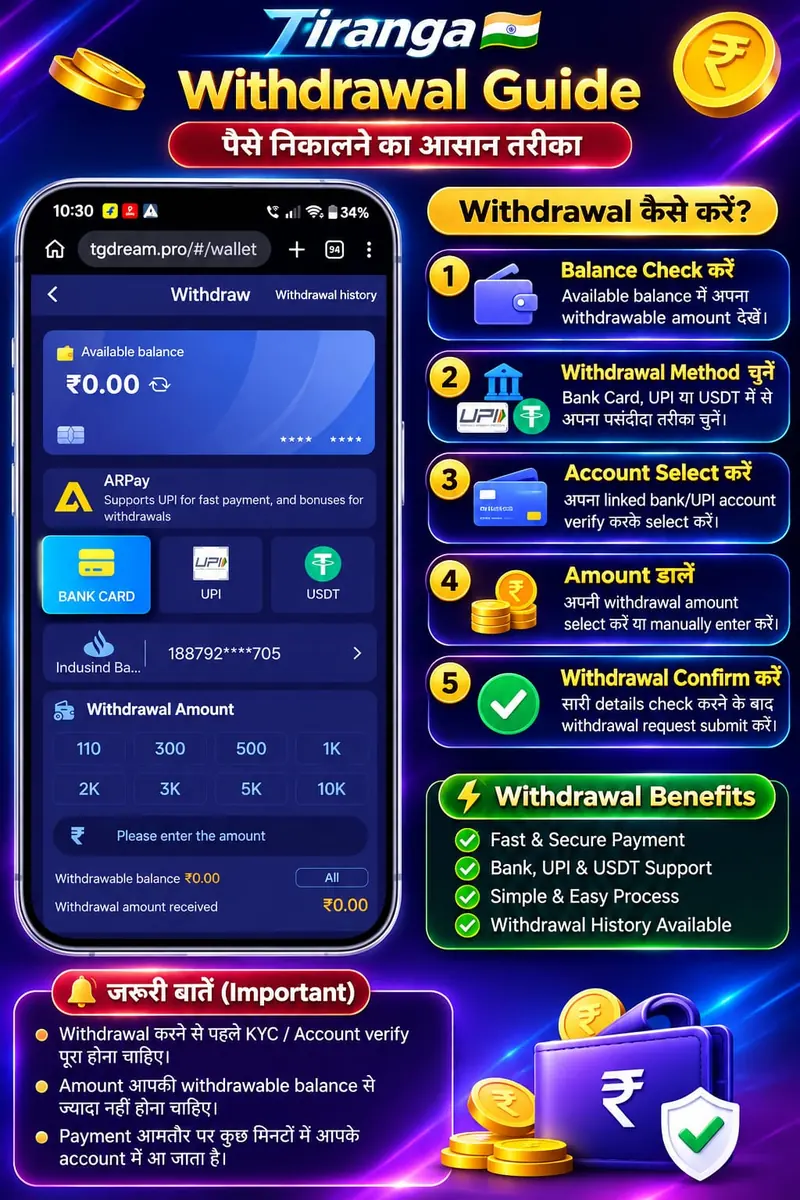
The withdrawal screen shows two figures. Available balance is everything in your wallet. Withdrawable balance is the part you can take out. The gap is usually:
- Bonus money, which must be wagered a number of times first. Promoters cite 2–5×.
- A deposit you haven’t bet through, since many platforms require each deposit to be wagered once before withdrawal.
- A pending bet that hasn’t settled.
If the withdrawable figure is lower than you expected, that is the most likely reason, and it isn’t necessarily fraud.
Minimums and timings: what promoters claim
| Item | Claims seen |
|---|---|
| Minimum deposit | ₹100 |
| Minimum withdrawal | ₹100, ₹110, $10 USDT, ₹200, ₹1,000, ₹5,000 |
| Withdrawal time | “5 minutes”, “a few hours”, “up to 72 hours” |
| Sign-up bonus | “₹600 free” (needs a ₹100 deposit and 2–5× wagering) · “₹5,000 welcome” (no terms shown) |
The withdrawal screen in circulating screenshots shows preset amounts starting at 110. Check your own app. Don’t trust a figure from a page that ends with an invite code.
Problem → likely cause → what to do
| Problem | Likely cause | Action |
|---|---|---|
| Withdraw button greyed out | Withdrawable balance below minimum, KYC not done, or bank not bound | Check the withdrawable figure and KYC status |
| Withdrawal “processing” for days | Manual review, payment channel problems, or deliberate delay | Message support once with the order ID; don’t place new deposits |
| Withdrawal rejected | Wrong bank details, “turnover not met”, or “abnormal betting” flag | Ask for the written reason; fix details if wrong; screenshot everything |
| “Successful” in app, not in bank | Payment never sent, sent to wrong account, or bank reversal | Check your bank statement and UTR (below); then escalate |
| Deposit paid, not credited | Payment to a third-party channel that didn’t report it | Submit UTR in app; if not fixed, raise a UPI dispute |
| Asked to pay to release money | Scam | Don’t pay. Report to 1930. |
Why deposits are hard to trace
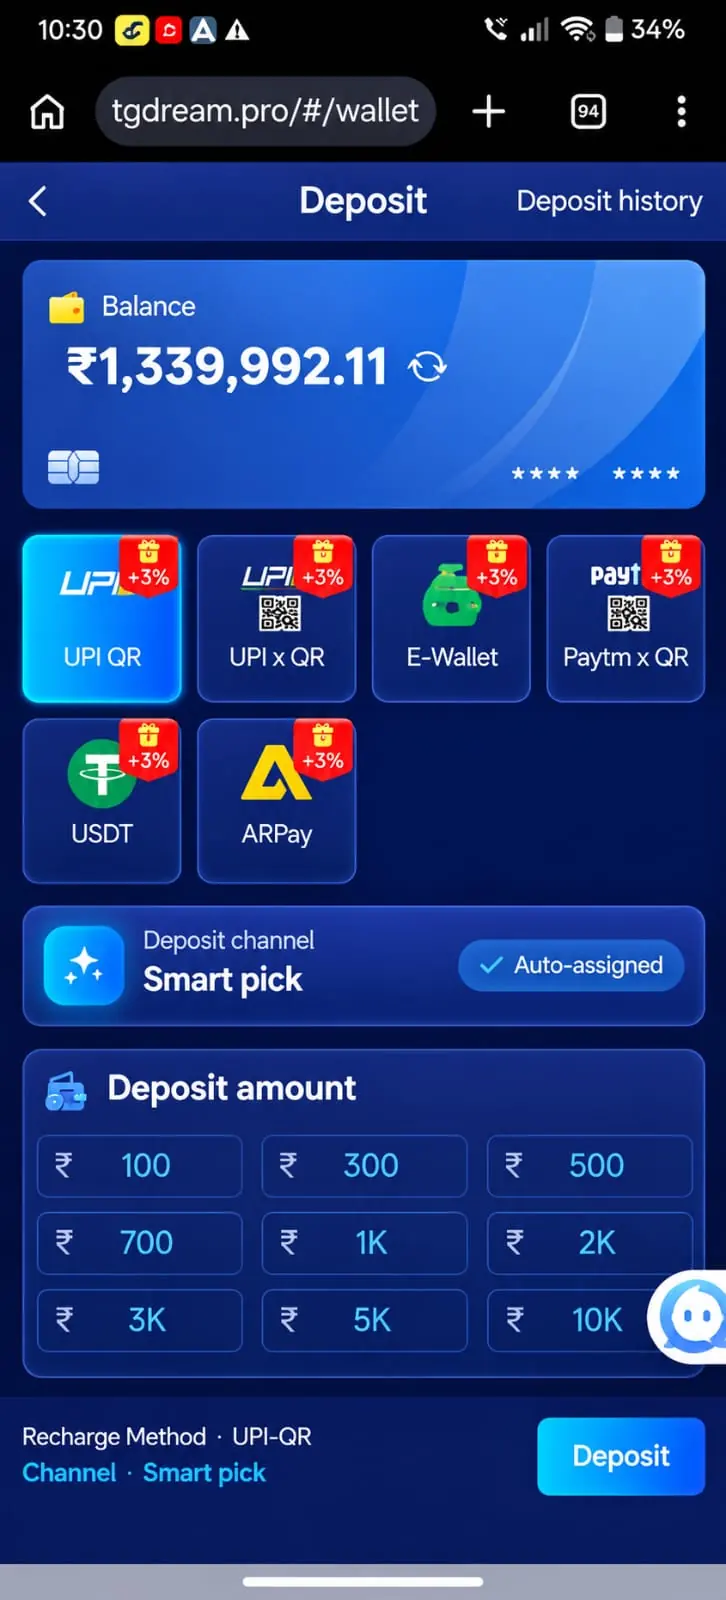
The deposit screen offers UPI QR, “UPI × QR”, e-wallet, Paytm QR, USDT and “ARPay”, with the channel “auto-assigned”. In practice the money goes to a third-party collector, whose name you see as the UPI payee: an individual or a shop, often different each time. Since 1 May 2026, banks must check that a game is registered before processing its payments. That is why transfers to such platforms can fail, bounce or be reversed.
Paying in USDT
Crypto deposits on the TRON network can’t be charged back, and recovering them is far harder than a UPI dispute. If a support agent pushes you to “switch to USDT for faster withdrawal”, treat that as a warning sign.
Evidence checklist
- Screenshot of available and withdrawable balance, with date and time visible.
- The withdrawal order ID and its status screen.
- For deposits: the UPI transaction ID / UTR (12 digits), amount, date, and the payee name shown in your UPI app.
- Your bank statement line, or its absence, for the same date.
- Chat transcripts with support, and the site address you used.
Escalation ladder
- In-app support, once, with the order ID and screenshots.
- Your UPI app / bank: raise a dispute on the specific transaction from the transaction’s page. For unresolved bank complaints, the RBI’s Banking Ombudsman route is next.
- Cyber fraud report: 1930 or cybercrime.gov.in, especially if you were asked to pay fees, or if money left your account without your consent. Report fast, because funds can sometimes be frozen in transit.
- Consumer helpline 1915, for record and guidance. It can’t act against an anonymous offshore operator, but it documents the complaint.
See also the full help page and what to send to support.